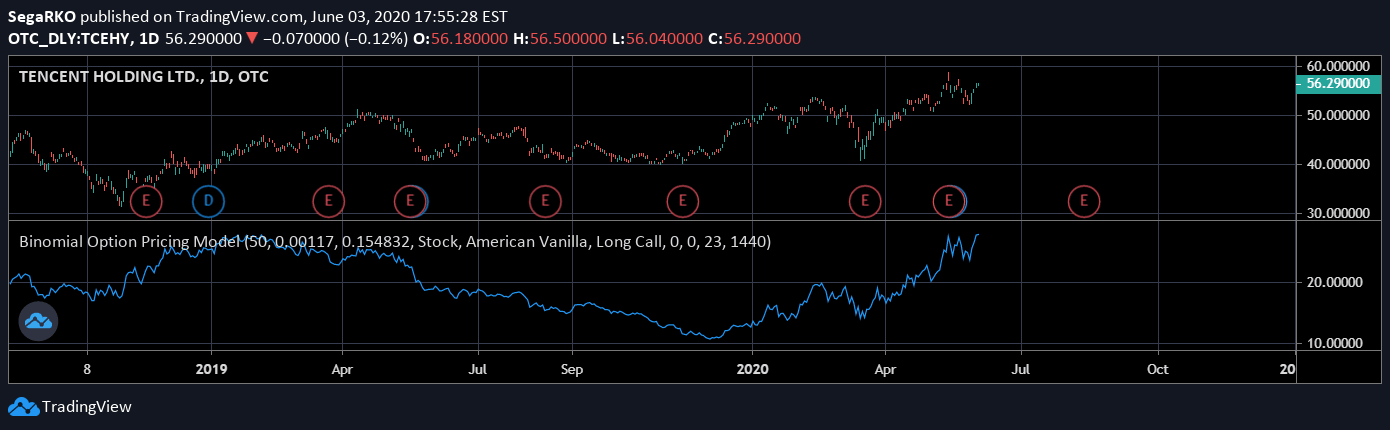
A binomial option pricing model that calculates option prices using a two-step tree method, allowing flexible pricing for American and European style options across different asset types.
Explore complementary indicator rolesHow it works
The binomial option pricing model (BOPM) works by dividing the time until option expiry into two equal steps. For each step, the model projects potential underlying asset prices using volatility calculations.
At the terminal node, option prices are calculated based on these projected prices. Using backwards induction, the model then calculates option prices at previous nodes, ultimately determining the current option's fair value by considering potential price movements and exercise scenarios
Why it may be useful
The BOPM provides traders with a more flexible approach to option pricing compared to traditional models like Black-Scholes. It allows for pricing complex option styles such as American and Bermudan options, which can be exercised early.
By modeling potential price paths and considering multiple scenarios, traders can gain more nuanced insights into option valuations across different asset classes like stocks, forex, and futures
When to explore it
This model is most effective when pricing options on assets with lower prices (under $100) and when you need to evaluate early exercise potential. It works best for traders wanting detailed option valuation that accounts for multiple potential price paths.
The model is particularly useful for options on stocks with moderate volatility, currency pairs, and futures contracts where precise pricing requires considering different potential market scenarios
Keep exploring
What we’ve verified
Access, alerts and repainting behaviour have not been independently verified for this indicator. Check the creator’s current publication and settings.
General descriptions and classifications are recovered research. Verified details above identify the specific checks we have completed. Check the creator’s current publication for later changes.