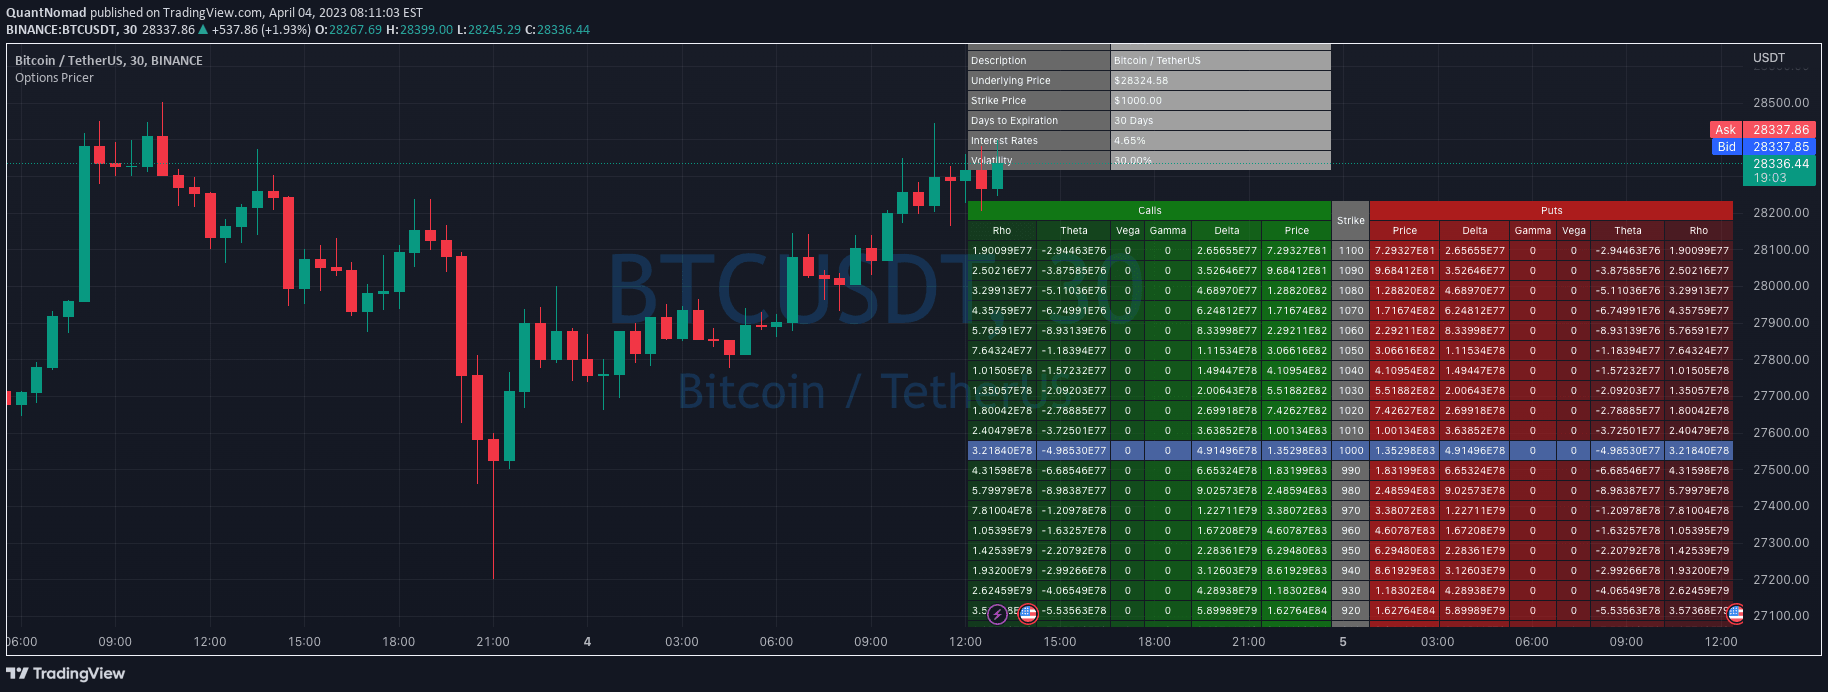
The Black-Scholes-Merton model is a sophisticated options pricing framework that calculates theoretical option values using key financial parameters and multiple Greek sensitivity measures.
Explore complementary indicator rolesHow it works
The Black-Scholes-Merton model calculates theoretical option prices using mathematical formulas that incorporate several key inputs. These include current stock price, strike price, risk-free interest rate, time to expiration, and implied volatility. The model generates a comprehensive set of Greek measurements that analyze how option prices change under different market conditions.
It provides a closed-form solution that efficiently estimates European call and put option values. Traders can input various parameters to understand potential option price movements and risk exposures. The model breaks down sensitivity across multiple dimensions, including price, time, volatility, and interest rates
Why it may be useful
The Black-Scholes-Merton model revolutionized options trading by providing a standardized approach to pricing complex financial instruments. It allows traders to quantify and manage risk more effectively by revealing how option values change under different scenarios. The model's Nobel Prize-winning methodology provides insights into potential price movements and hedging strategies.
By breaking down option sensitivity through multiple Greek measurements, traders can make more informed decisions. The framework helps financial institutions and individual traders understand potential market exposures. It transforms options pricing from an art to a more precise scientific approach
When to explore it
The Black-Scholes-Merton model works best when trading European-style options with predictable market conditions. It is most effective for liquid securities with stable volatility and clear market trends. Traders should use this model when they want comprehensive risk analysis across multiple financial parameters.
The model is particularly useful for options with shorter time to expiration and when implied volatility is relatively consistent. Professional traders and market makers rely on this model for portfolio risk management. It provides maximum value when combined with other analytical tools and comprehensive market research
Keep exploring
What we’ve verified
Access, alerts and repainting behaviour have not been independently verified for this indicator. Check the creator’s current publication and settings.
General descriptions and classifications are recovered research. Verified details above identify the specific checks we have completed. Check the creator’s current publication for later changes.